
The housing market is ugly right now. I’m not going to sugarcoat it.
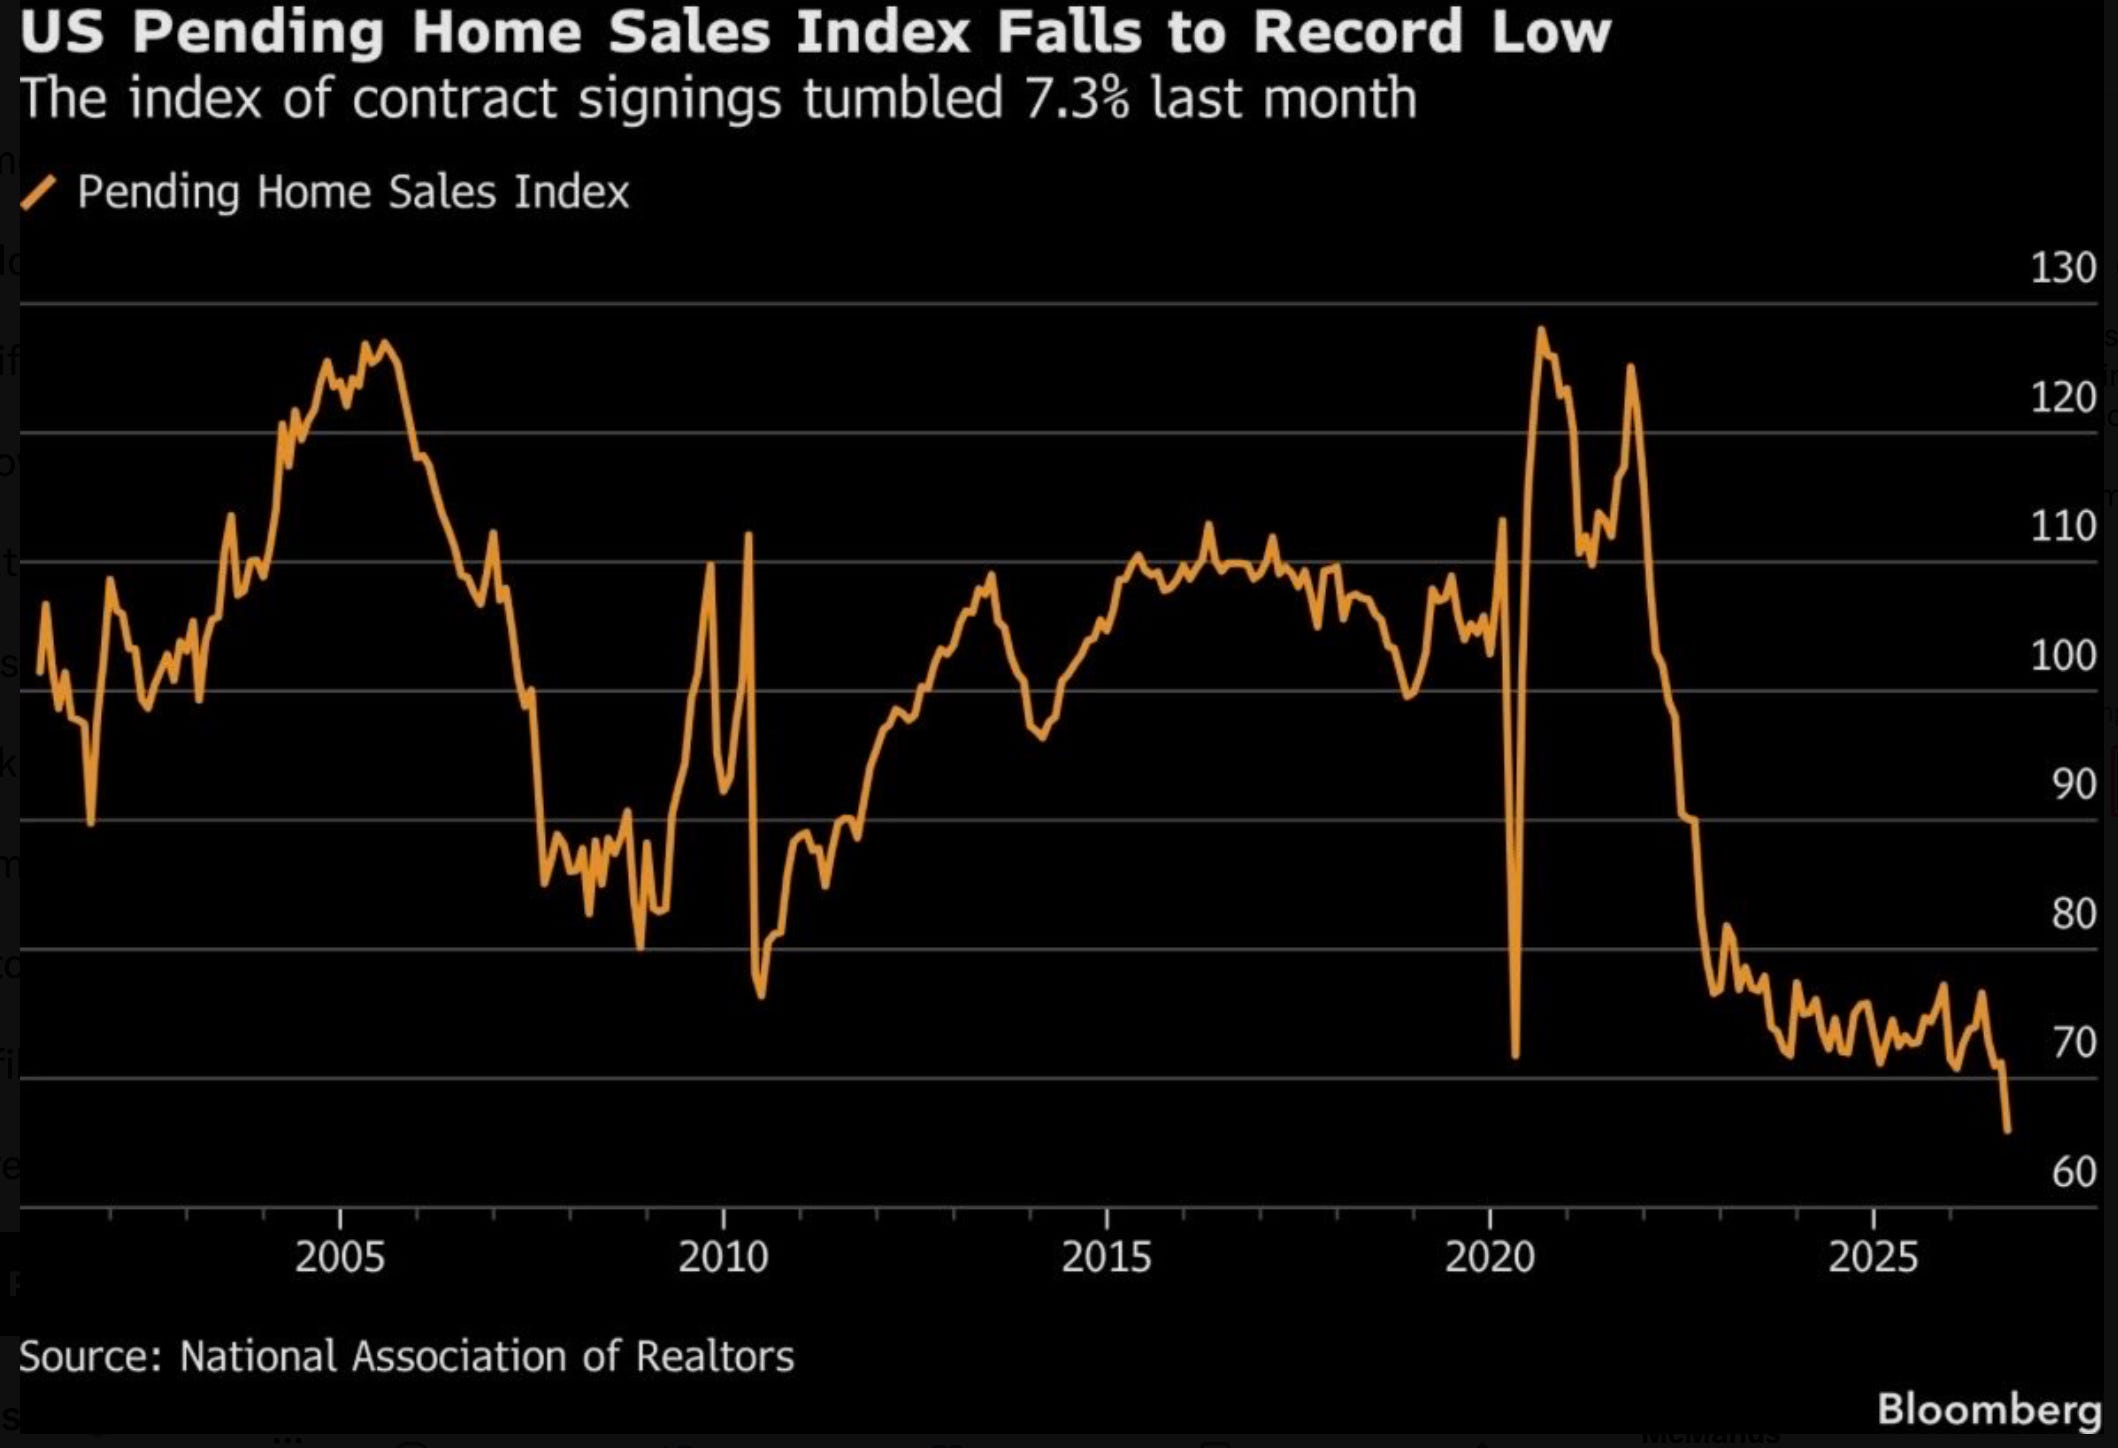
Pending home sales just fell to a record low.
Lower than during the financial crisis.
Lower than when the entire country was on lockdown for a pandemic.
Builders are feeling it too. Builder confidence just hit a 14-year low. 43% of them cut prices in October.
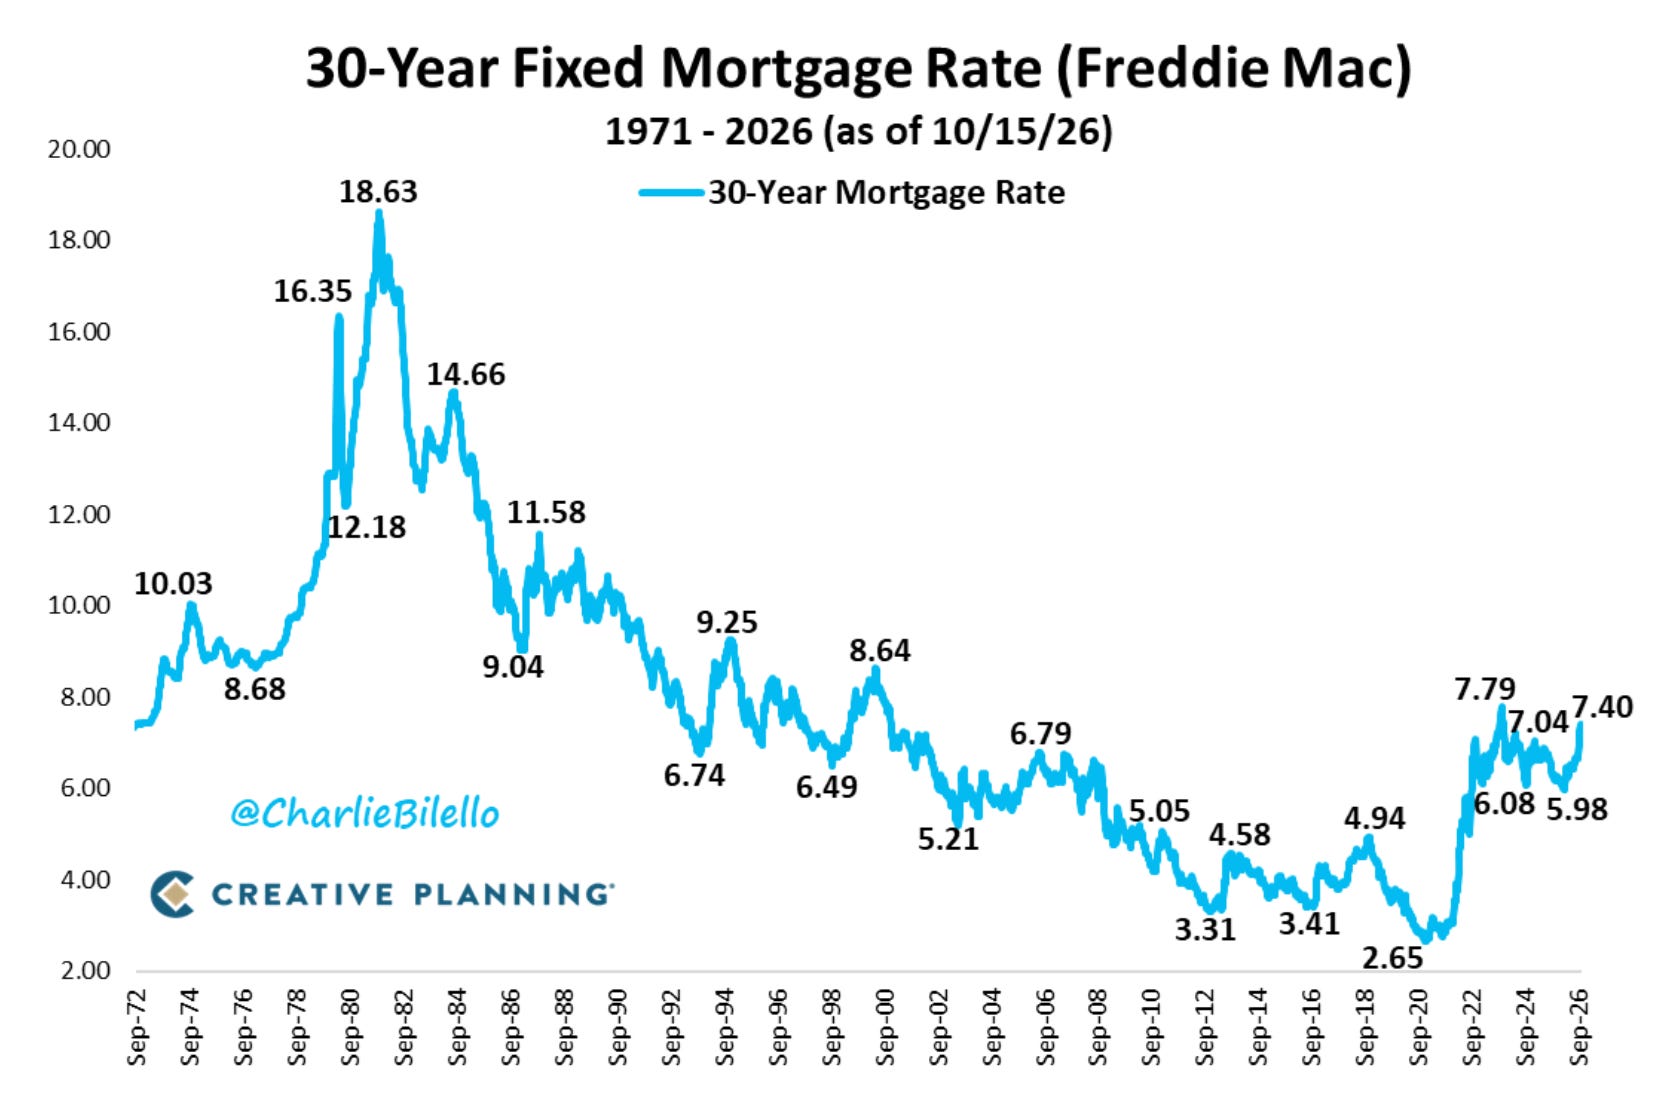
And the rate everyone is watching? The 30-year mortgage averaged 7.32% last week. A year ago it was 6.19%.
High? Sure. Historically crazy? Not even close. Back in 1981 it hit 18.63%.
So if you’re shopping for a house right now, or thinking about trading up, I get it. The easy move is to throw up your hands and say I’ll just wait.
Wait for what?
You Can Be Right and Still Be Wrong
You can be completely right that the housing market is terrible. And still be wrong to wait.
Waiting feels safe. It feels responsible. But waiting is a decision too. And it comes with a price tag nobody talks about.
What Are You Waiting For
Lower rates? Maybe. Or maybe they go higher. Nobody knows. What if rates stay up here for three to five years? You waited five years for nothing.
And if rates do drop? Great. Every buyer sitting on the sidelines comes rushing back. Remember 2021? Bidding wars. Waived inspections. Offers way over asking. A lower rate on a higher price with ten other buyers in the driveway. Is that what you’re waiting for?
Lower prices? Home prices are still near record highs. The latest Case-Shiller data has them up 2.7% over the past year. They haven’t come down.
The perfect house? Who knows what will be available when you’re finally ready. The one you love might be gone.
There are way too many what-ifs. And almost none of them are in your control.
The Crash Everyone Is Waiting For
When people say they’re waiting, a lot of them have 2008 in the back of their mind.
The financial crisis was brutal. National home prices fell roughly 27% and didn’t get back to their old peak until 2016. It was a perfect storm. Reckless lending, overbuilding, and a banking system that nearly broke.
What really crushed prices was forced selling. In 2009, more than half a million mortgages a quarter entered foreclosure. Today it’s a sliver of that. People aren’t being forced out. They’re sitting on low rates and real equity.
It happened. It could happen again. But waiting for a repeat is a gamble and not a plan.
And that was 18 years ago, friends. If you’re waiting for a repeat, you might be waiting the rest of your life.
Here’s the long view.
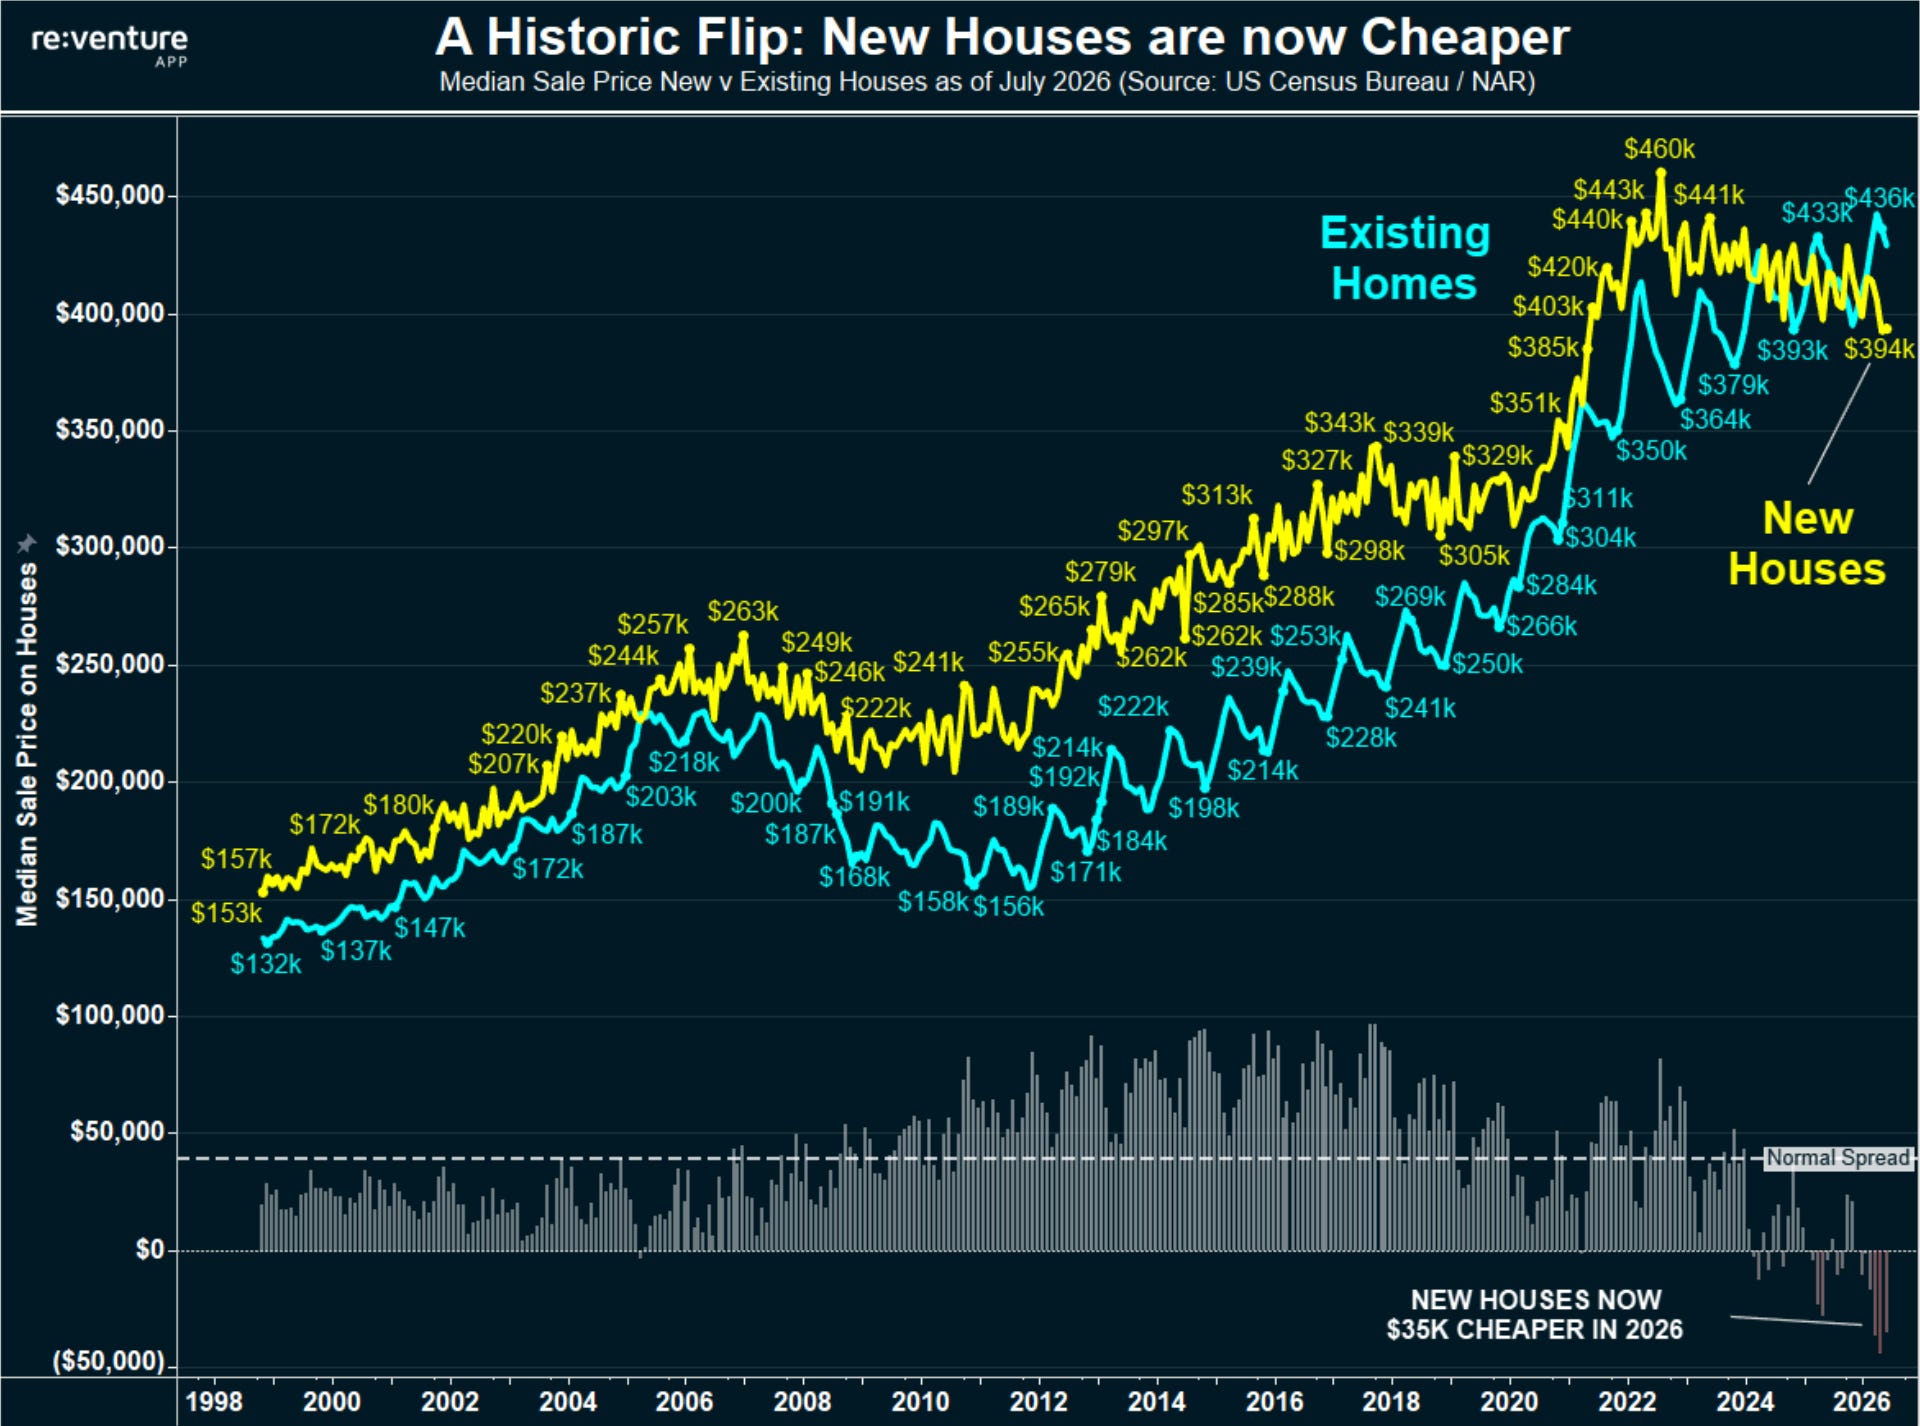
A median existing home went for about $153,000 in 1998. Today it’s over $400,000. The GFC is the dip everyone remembers. Zoom out and it’s a speed bump.
Hang on to this chart. We’ll come back to it.
What If You Bought at the Worst Time
Think about someone who bought in 2021. Everyone said it was insane. Bidding wars on every listing. Paying well over asking.
That buyer locked in a mortgage around 3%. The median existing home sold for roughly $347,000 that year. This September it was $417,500.
The “worst time ever to buy” looks pretty good now.
Even someone who bought at the mid-2022 peak is doing fine. The median sale price is about flat since then, and the Case-Shiller index has national home values up around 9%. Some markets are underwater, no question. But if you bought a home you could afford and planned to stay in, it looks a lot better than the headlines said. And you’ve been living in it for four years instead of waiting.
The Costs You Can’t Control
Everyone fixates on two numbers. The price and the rate.
That’s only part of it.
Every home I’ve built cost more than the last one. Not a little more. A lot more. Lumber, concrete, windows, labor. Ask any builder what a house cost to build ten years ago. Then ask them what it costs today.
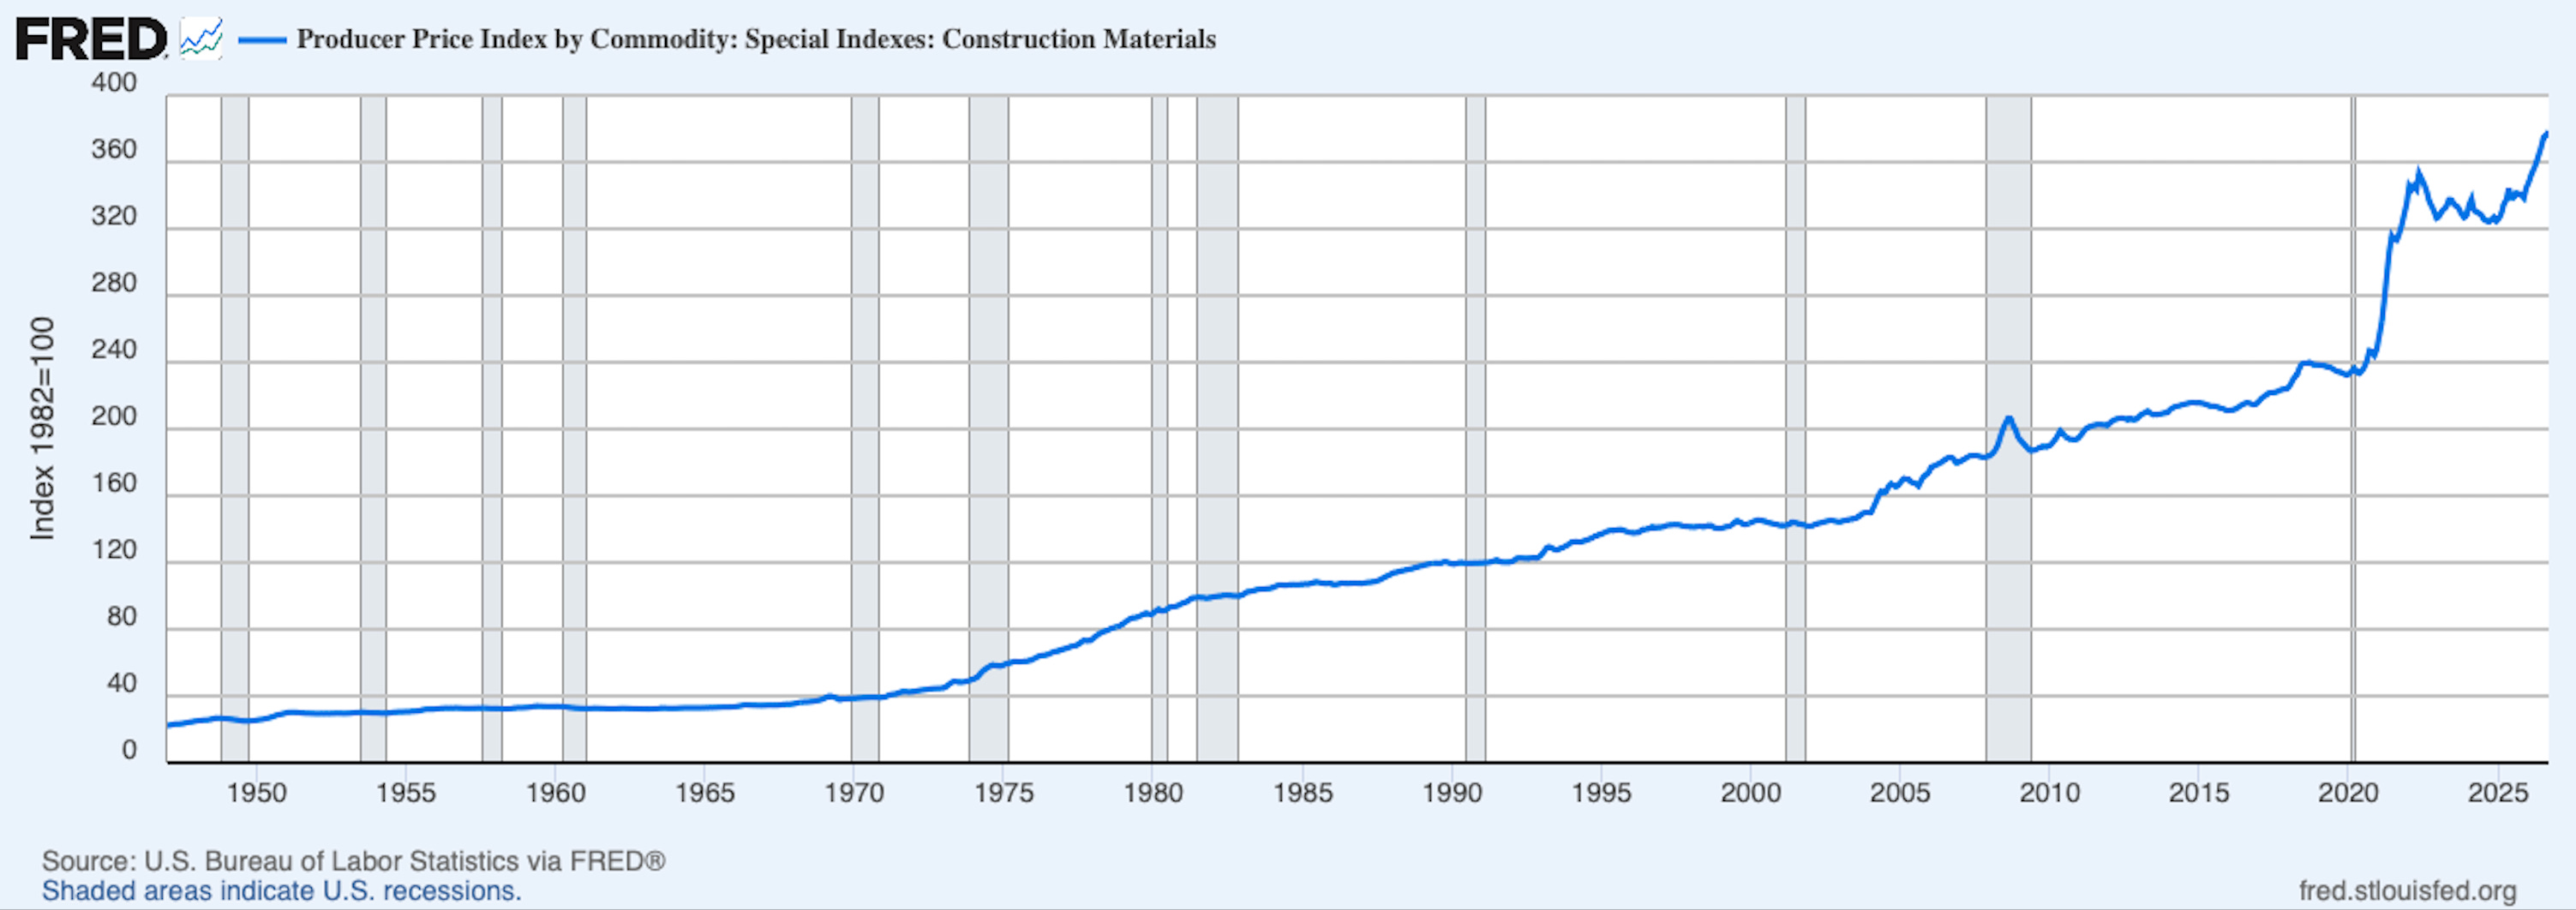
Construction materials are at an all-time high. They jumped in 2021 and 2022 and never came back down.
And it’s not just building. Same goes for any remodel or renovation.
Thinking about buying a house and updating the kitchen later? Finishing the basement? New flooring, paint, a roof? Those costs aren’t waiting for you. They’re going up while you wait.
Then there’s the contractor. Every time I’ve built, the good ones were booked out months. That’s never changed.
Add property taxes and insurance on top of that.
Just assume most of it costs more in 1, 2, 3, and 5 years. History is pretty clear on this.
The trade-up crowd should pay extra attention here. You’re not just buying a bigger house. You’re buying the changes you’ll want to make to it. Those only get more expensive.
You Need Shelter Either Way
This is the part almost nobody talks about.
So here’s the real choice. Buy a home with a 7%+ mortgage at a price that feels high? Or keep renting?
If you’re renting, which way do you think your rent is going?
Rents have basically gone flat the last couple of years. Why? A once-in-a-generation apartment building boom flooded the market with new units.
That boom is over. Apartment construction keeps falling. Fewer new units means less competition for landlords. You know what that means for your rent.
You have to live somewhere. Rent or own, shelter costs way more than it did five or ten years ago. And it’ll almost certainly cost more five years from now.
Renting isn’t free while you wait for the market to cooperate.
This Is a Buyer’s Market
Here’s what gets lost in all the doom.
The housing market is frozen. That’s bad for sellers. It’s not bad for you.
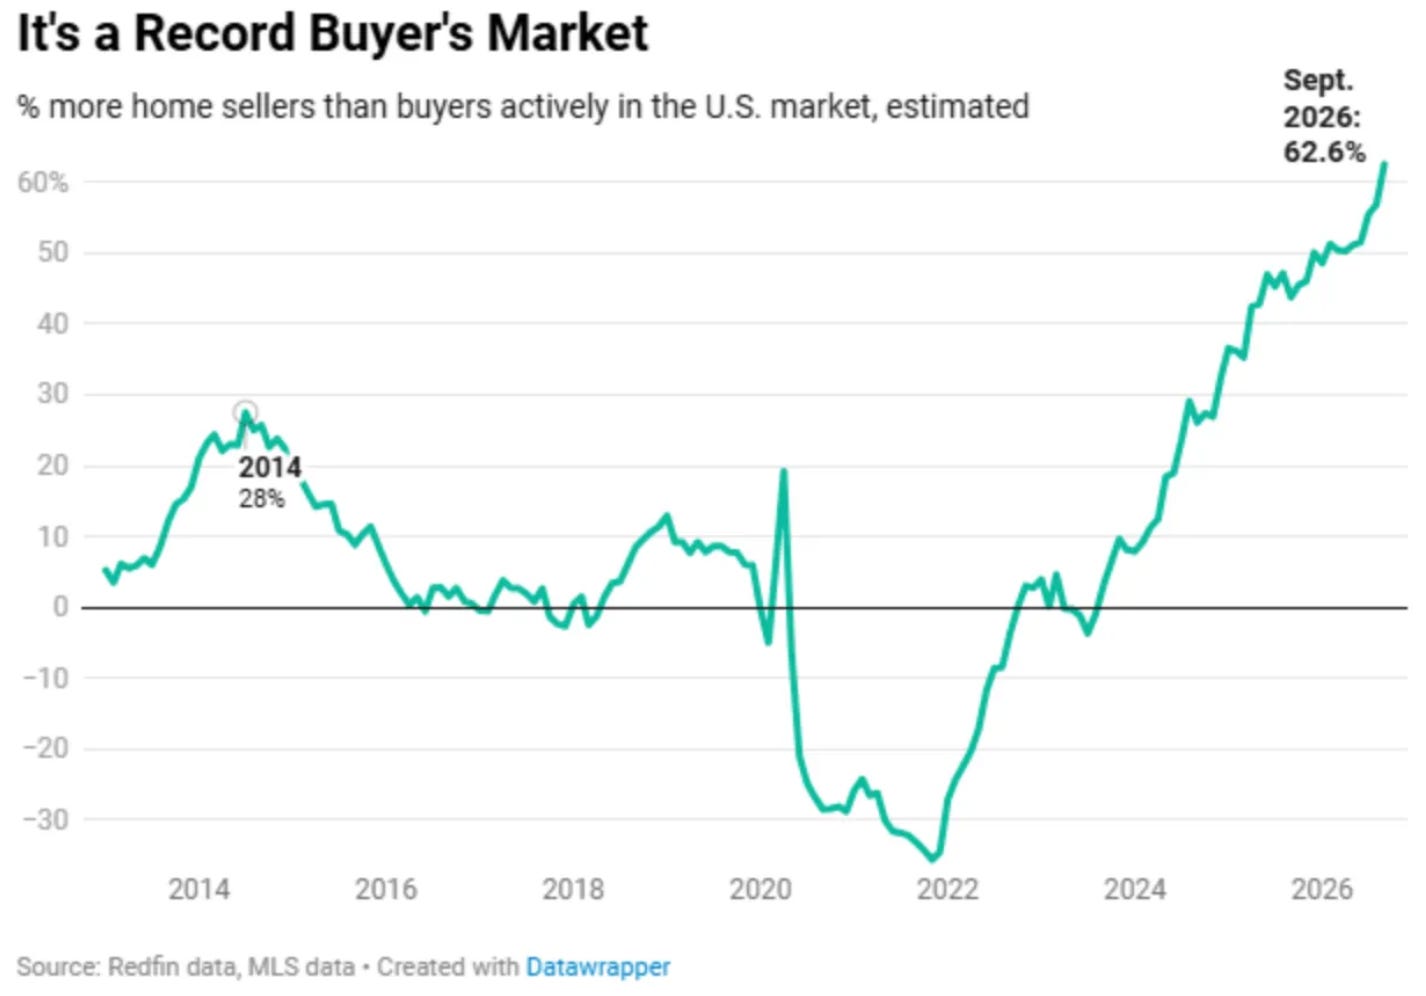
There are 62.6% more sellers than buyers right now. A record. In 2021 and 2022 it was the opposite. Buyers outnumbered sellers by more than 30%, and you know how that went.
Now go back to that long-view chart. New homes are now about $35,000 cheaper than existing homes. Builders are cutting prices and throwing in incentives just to move inventory.
That’s negotiating power. Price cuts. Seller concessions. Builders paying to buy down your rate.
Inspections are back. Negotiating is back. Walking away is back.
You don’t need to time the market. But if you’re ready, these are conditions buyers in 2021 would have killed for.
The Math on Waiting
Let’s make it real.
Two people. Same $450,000 house. One buys now at 7.32%. One waits a year. Prices rise 2.5% in that year, about what they did last year. Now that house costs $11,250 more.
Rates drop to 6.5%. Waiting wins, right? Not so fast. The buyer refinances. Now they have the lower rate and last year’s price. The waiter gets the same rate on a house that costs $11,250 more. A refinance isn’t free. But even after closing costs, the buyer comes out ahead.
Rates stay put. Same rate. Higher price. Buyer wins.
Rates hit 8%. Buyer wins big.
Waiting only really wins if prices stall or fall.
Look at everything above. Foreclosures near historic lows. Nobody being forced to sell. Building costs at a record. That’s the bet you’re making when you wait.
Don’t Let the Rate Make the Decision
If you love the place. If you love the area. If your family’s happiness meter jumps every time you walk in the door. And you can comfortably afford it. It’s a no-brainer.
The difference between 7.3% and 6.5% on a $400,000 loan? About $220 a month. That’s the trade.
If rates fall later, you can refinance. You can’t refinance into a house someone else bought.
Now, if you can’t comfortably afford it, or you might move in two years, rent. That’s not timing the market. That’s just simple math.
Nobody Wishes They Waited
I’ve built three homes since 2008. Through the crash, the recovery, and the COVID frenzy. Every one built for my family, not as an investment. And I bought a cottage last month. In this market.
I have never once looked back and thought “I should have waited.”
Sure, some people regret buying. But plenty of people regret waiting for a moment that never came.
The housing market stinks. It could stay this way for a while. It could get worse. I’m not sure. Nobody knows.
That’s exactly the point.
You don’t need to predict the housing market. You need a home that works for your finances and your life.
So what exactly are you waiting for?
Thank you for reading! If you enjoyed Spilled Coffee, please subscribe.
Spilled Coffee grows through word of mouth. Please consider sharing this post with someone who might appreciate it.